How Much Do You Need to Earn to Buy a Home in 2026?
Key Takeaways
- San Jose requires the highest salary to buy a median-priced home at $492.4K, nearly seven times the $71.6K needed in Pittsburgh.
- Buyers need a six-figure salary in 32 of the 50 major U.S. metros, including more than $200K in seven.
- Just two metros, Pittsburgh and Cleveland, have median household incomes above the salary needed to buy a home.
A six-figure salary used to be a benchmark of financial success. In much of the U.S. housing market, it’s now closer to the starting point for buying a home, even with a substantial down payment.
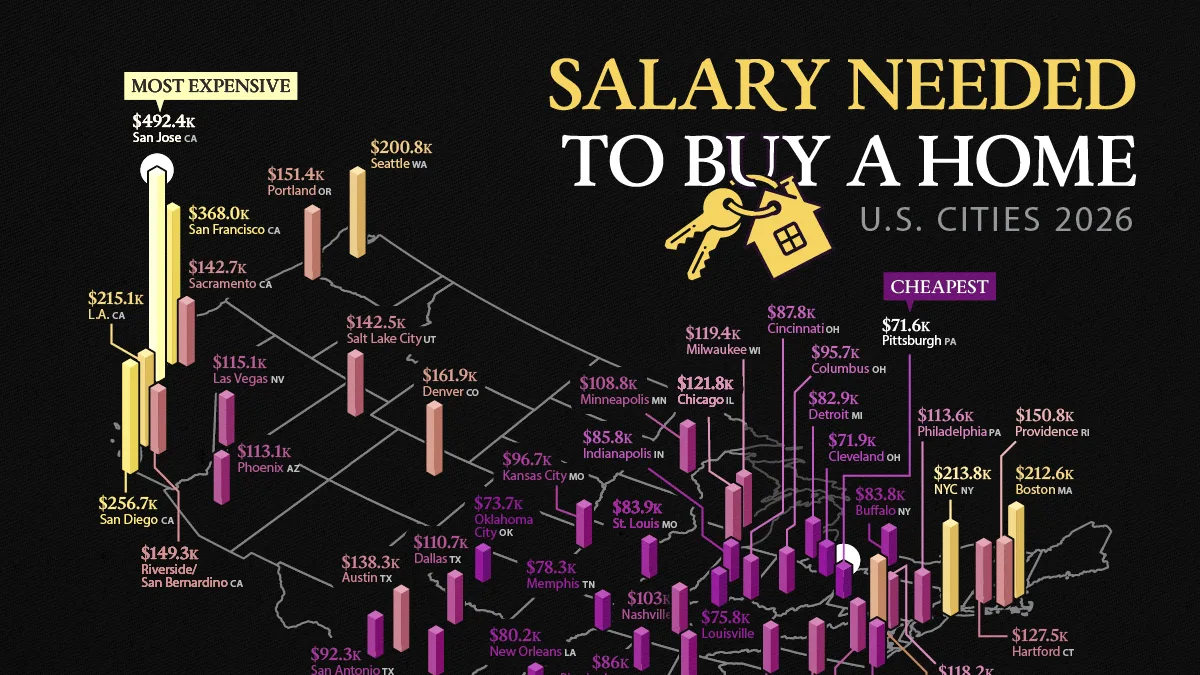
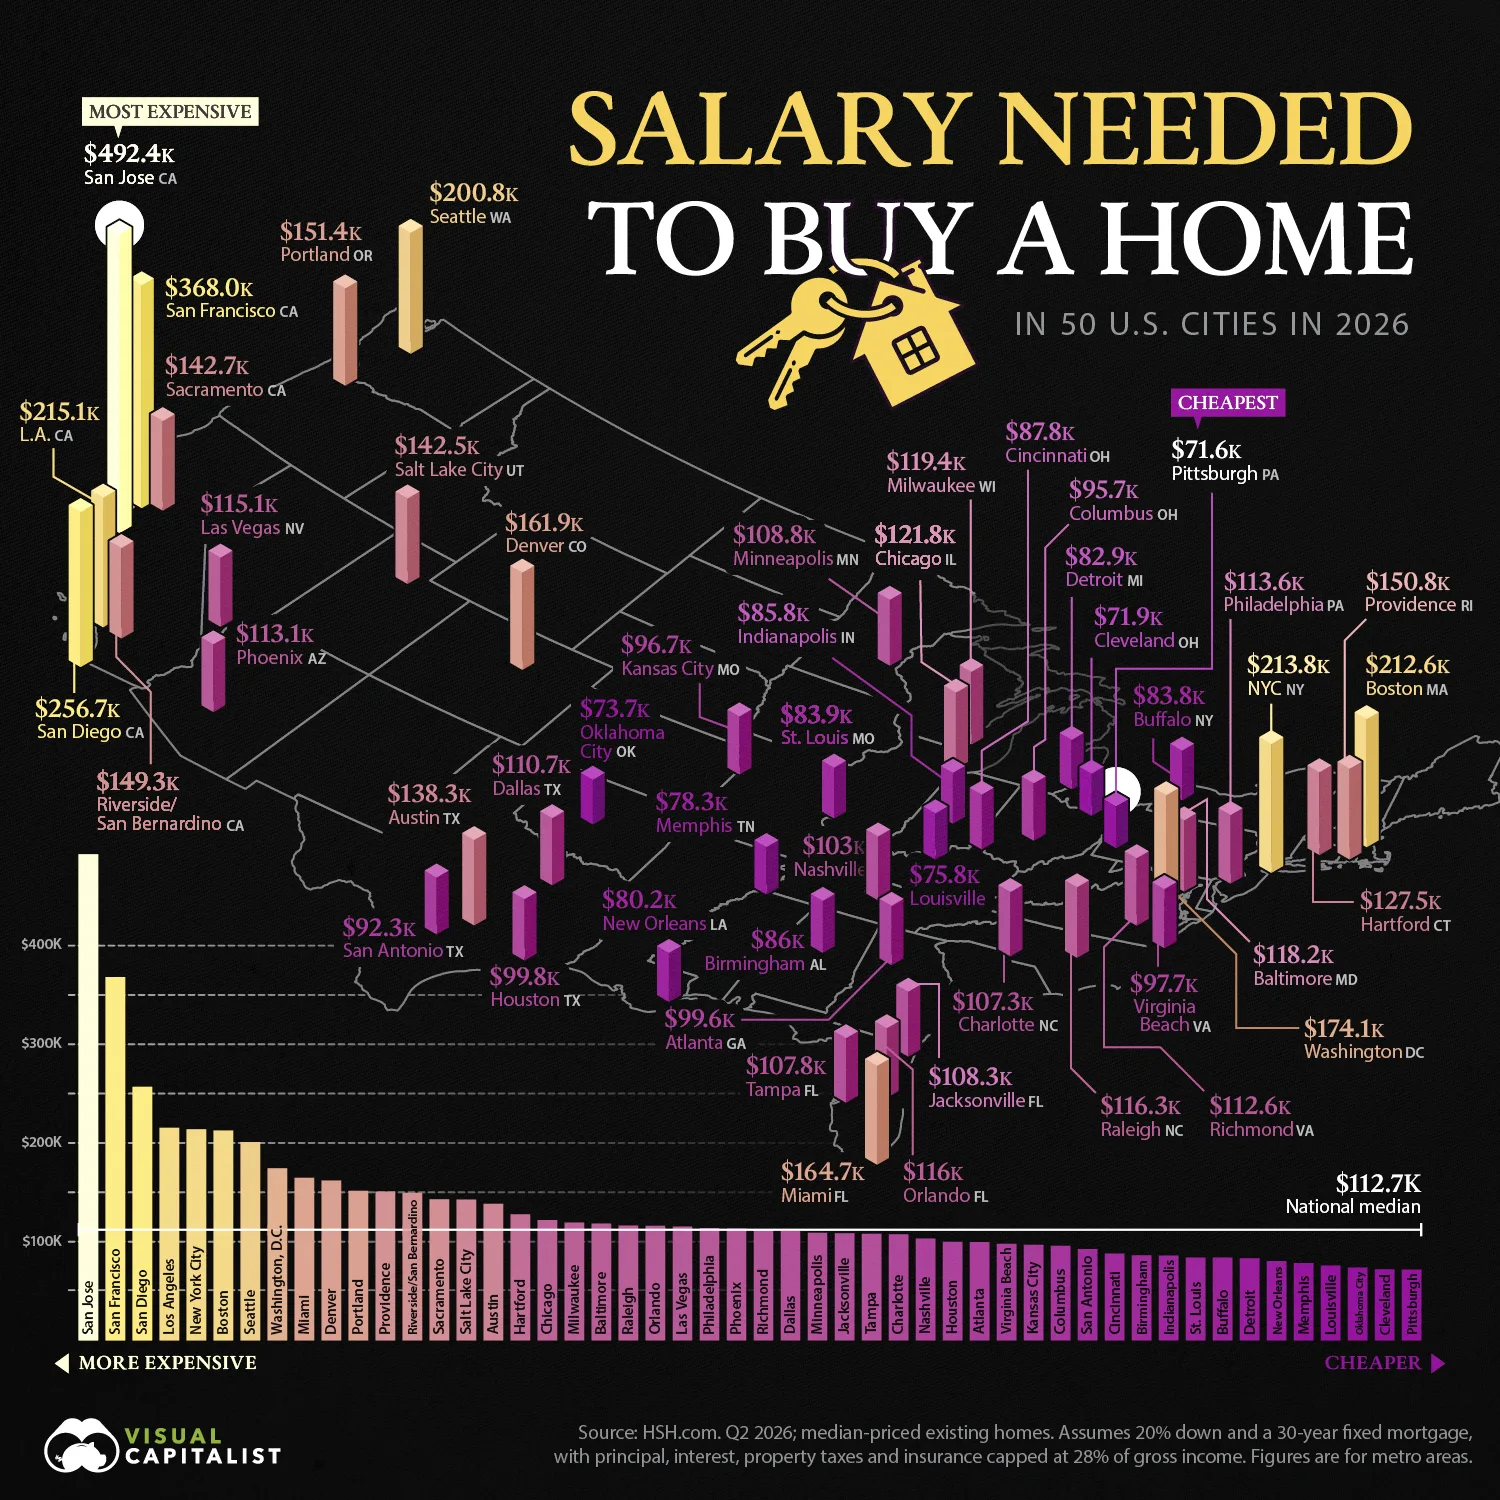
This map shows the annual income needed to buy a median-priced existing home in 50 major U.S. metro areas in Q2 2026, using data from HSH.com. It assumes a 20% down payment and a 30-year fixed mortgage, with principal, interest, property taxes, and insurance taking up 28% of gross income.
California Metros Need the Highest Salaries
California dominates the expensive end of the ranking. San Jose leads at $492.4K a year, followed by San Francisco ($368.0K), San Diego ($256.7K), and Los Angeles ($215.1K).
Outside California, New York City ($213.8K), Boston ($212.6K), and Seattle ($200.8K) are the only metros requiring annual incomes above $200K.
The table below ranks all 50 metro areas by the income needed to buy a median-priced home, along with each metro’s median home price and monthly mortgage payment:
| Rank | Metro Area | Q2 2026 (USD) | ||
|---|---|---|---|---|
| Income Needed to Buy a Home | Median Home Price | Monthly Payment | ||
| 1 | San Jose | 492,364 | 2,050,000 | 11,489 |
| 2 | San Francisco | 367,973 | 1,500,000 | 8,586 |
| 3 | San Diego | 256,735 | 1,075,000 | 5,990 |
| 4 | Los Angeles | 215,136 | 879,900 | 5,020 |
| 5 | New York City | 213,791 | 802,400 | 4,988 |
| 6 | Boston | 212,586 | 844,600 | 4,960 |
| 7 | Seattle | 200,835 | 815,000 | 4,686 |
| 8 | Washington | 174,110 | 688,200 | 4,063 |
| 9 | Miami | 164,691 | 659,000 | 3,843 |
| 10 | Denver | 161,920 | 668,300 | 3,778 |
| 11 | Portland | 151,400 | 611,100 | 3,533 |
| 12 | Providence | 150,771 | 580,900 | 3,518 |
| 13 | Riverside/San Bernardino | 149,302 | 605,000 | 3,484 |
| 14 | Sacramento | 142,726 | 560,000 | 3,330 |
| 15 | Salt Lake City | 142,461 | 601,200 | 3,324 |
| 16 | Austin | 138,268 | 485,400 | 3,226 |
| 17 | Hartford | 127,510 | 456,700 | 2,975 |
| 18 | Chicago | 121,817 | 438,600 | 2,842 |
| 19 | Milwaukee | 119,354 | 466,500 | 2,785 |
| 20 | Baltimore | 118,198 | 458,400 | 2,758 |
| 21 | Raleigh | 116,261 | 466,700 | 2,713 |
| 22 | Orlando | 115,986 | 450,000 | 2,706 |
| 23 | Las Vegas | 115,133 | 486,300 | 2,686 |
| 24 | Philadelphia | 113,570 | 419,800 | 2,650 |
| 25 | Phoenix | 113,144 | 477,700 | 2,640 |
| 26 | Richmond | 112,640 | 460,400 | 2,628 |
| 27 | Dallas | 110,651 | 380,100 | 2,582 |
| 28 | Minneapolis | 108,829 | 414,300 | 2,539 |
| 29 | Jacksonville | 108,295 | 417,500 | 2,527 |
| 30 | Tampa | 107,829 | 415,000 | 2,516 |
| 31 | Charlotte | 107,287 | 434,000 | 2,503 |
| 32 | Nashville | 103,046 | 420,900 | 2,404 |
| 33 | Houston | 99,848 | 345,200 | 2,330 |
| 34 | Atlanta | 99,594 | 387,000 | 2,324 |
| 35 | Virginia Beach | 97,743 | 387,000 | 2,281 |
| 36 | Kansas City | 96,683 | 370,600 | 2,256 |
| 37 | Columbus | 95,705 | 363,100 | 2,233 |
| 38 | San Antonio | 92,337 | 316,500 | 2,155 |
| 39 | Cincinnati | 87,772 | 341,500 | 2,048 |
| 40 | Birmingham | 85,983 | 352,200 | 2,006 |
| 41 | Indianapolis | 85,826 | 343,900 | 2,003 |
| 42 | St. Louis | 83,886 | 314,100 | 1,957 |
| 43 | Buffalo | 83,772 | 287,800 | 1,955 |
| 44 | Detroit | 82,913 | 311,800 | 1,935 |
| 45 | New Orleans | 80,193 | 304,200 | 1,871 |
| 46 | Memphis | 78,344 | 308,900 | 1,828 |
| 47 | Louisville | 75,811 | 297,400 | 1,769 |
| 48 | Oklahoma City | 73,747 | 269,900 | 1,721 |
| 49 | Cleveland | 71,871 | 258,500 | 1,677 |
| 50 | Pittsburgh | 71,567 | 267,700 | 1,670 |
| — |  National Average |
112,695 | 434,900 | 2,630 |
All 12 Western metros require more than the national figure of $112.7K, while the cheaper half of the ranking consists of Southern and Midwestern metros, plus Buffalo and Pittsburgh.
In coastal California, much of what buyers pay for is the land itself. Land accounted for 59% to 68% of a single-family home’s value in the San Jose, San Francisco, Los Angeles, and San Diego metros in 2022, compared with 40% nationally and 22% in Pittsburgh, according to FHFA estimates.
In Most Metros, Typical Households Earn Too Little to Buy
Nationally, buyers needed $112.7K a year, about 29% more than the 2025 U.S. median household income of $87.5K, according to the Census Bureau.
The gap between home prices and household incomes is especially striking in San Jose. Although the typical household earns roughly twice the national median, the median home costs nearly five times as much as the national median. As a result, the typical local household earns only about one-third of the income needed to buy a median-priced home.
At the other end of the ranking, these five metros require the lowest salaries:
- Pittsburgh: $71.6K
- Cleveland: $71.9K
- Oklahoma City: $73.7K
- Louisville: $75.8K
- Memphis: $78.3K
Based on 2024 Census data, the latest available by metro area, median household incomes in Oklahoma City and Louisville fell short of the required salaries by less than 2%.
Homebuying Got Easier in the South and West
Compared with Q2 2025, the income needed fell in 30 of the 50 metros as the average 30-year mortgage rate dropped from 6.79% to 6.41%.
However, the required income rose in 13 of the 17 Midwest and Northeast metros, led by St. Louis (+3.8%), Hartford (+3.6%), and Providence (+3.3%). Even Pittsburgh and Cleveland, the two cheapest markets, became less affordable.
New construction helps explain the regional divide. The South and West accounted for 79% of single-family housing starts in 2025, despite holding about 63% of the U.S. population, according to Census Bureau data. All 10 metros where home prices fell were also in those two regions.
The table below shows how the income needed and median home prices changed in each metro from Q2 2025 to Q2 2026:
| Metro Area | State | Region | Change, Q2 2025 to Q2 2026 (%) | |
|---|---|---|---|---|
| Income Needed to Buy a Home | Median Home Price | |||
| St. Louis | MO | Midwest | 3.76 | 6.22 |
| Hartford | CT | Northeast | 3.56 | 7.97 |
| Providence | RI | Northeast | 3.28 | 7.43 |
| Pittsburgh | PA | Northeast | 2.95 | 6.78 |
| Milwaukee | WI | Midwest | 2.93 | 6.85 |
| New York City | NY | Northeast | 2.53 | 6.03 |
| Jacksonville | FL | South | 2.45 | 5.43 |
| Detroit | MI | Midwest | 2.45 | 6.09 |
| Cleveland | OH | Midwest | 2.44 | 6.20 |
| Kansas City | MO | Midwest | 2.37 | 4.45 |
| Cincinnati | OH | Midwest | 2.18 | 5.53 |
| Chicago | IL | Midwest | 2.05 | 5.74 |
| San Francisco | CA | West | 1.73 | 5.19 |
| San Diego | CA | West | 1.21 | 4.88 |
| Virginia Beach | VA | South | 0.91 | 3.98 |
| Buffalo | NY | Northeast | 0.75 | 3.45 |
| Richmond | VA | South | 0.63 | 3.79 |
| New Orleans | LA | South | 0.46 | 2.15 |
| Columbus | OH | Midwest | 0.18 | 3.21 |
| Tampa | FL | South | 0.16 | 2.47 |
| Baltimore | MD | South | -0.02 | 3.01 |
| Memphis | TN | South | -0.03 | 3.00 |
| Indianapolis | IN | Midwest | -0.39 | 2.20 |
| Birmingham | AL | South | -0.41 | 2.95 |
| Philadelphia | PA | Northeast | -0.46 | 3.73 |
| Miami | FL | South | -0.61 | 2.01 |
| Louisville | KY | South | -1.06 | 1.95 |
| Sacramento | CA | West | -1.08 | 1.82 |
| Charlotte | NC | South | -1.12 | 0.56 |
| Atlanta | GA | South | -1.43 | 0.91 |
| Salt Lake City | UT | West | -1.44 | 2.24 |
| Boston | MA | Northeast | -1.68 | 1.28 |
| San Antonio | TX | South | -1.80 | -0.31 |
| Oklahoma City | OK | South | -1.94 | 0.15 |
| Washington | DC | South | -1.98 | 0.92 |
| Orlando | FL | South | -2.04 | 0.04 |
| Denver | CO | West | -2.27 | 0.16 |
| Raleigh | NC | South | -2.32 | -0.83 |
| Minneapolis | MN | Midwest | -2.35 | 0.53 |
| Phoenix | AZ | West | -2.57 | 0.65 |
| Houston | TX | South | -2.60 | -1.20 |
| Dallas | TX | South | -2.76 | -0.68 |
| Las Vegas | NV | West | -2.85 | 0.25 |
| Austin | TX | South | -2.89 | -1.30 |
| Los Angeles | CA | West | -2.90 | 0.00 |
| Portland | OR | West | -3.38 | -0.60 |
| Riverside/San Bernardino | CA | West | -3.51 | -0.82 |
| Nashville | TN | South | -4.17 | -1.41 |
| Seattle | WA | West | -4.89 | -2.28 |
| San Jose | CA | West | -6.67 | -4.16 |
| National Average |
— | — | -1.12 | 1.49 |
Rising mortgage rates have since erased much of that relief. Freddie Mac’s average 30-year mortgage rate reached 7.40% in October 2026, its highest level since November 2023 and nearly a full percentage point above the Q2 average.
At that rate, buying the national median-priced home would require an annual income of approximately $122.6K, nearly $10K more than the Q2 figure. This illustrates how quickly borrowing costs can change affordability, even without a corresponding increase in home prices.
Learn More on the Voronoi App
If you enjoyed today’s post, check out Years of Income Needed to Buy a Home by State on Voronoi.