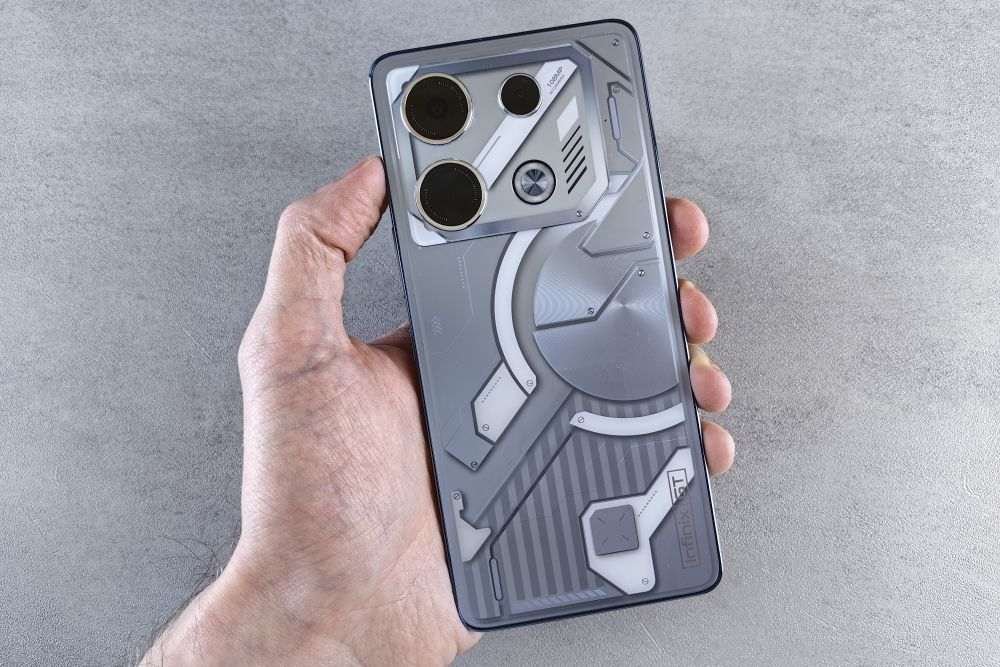
China is one of the fastest-growing sources of demand for biobased materials worldwide. A major factor in this is the big consumer tech firms.
Some of China’s largest consumer tech brands are adopting vegan leather, biobased packaging, and waste-based polymers. The growth is driven by regulations, consumer trends, and the desire for resource security.
When China consumes, markets listen. Here are the Chinese consumer brands adopting and investing in biomaterials.
Xiaomi
Some of the biggest biomaterials buyers in the world are Chinese consumer manufacturers. Many are among the most important brands in their segments worldwide. One of the most notable is Xiaomi, whose adjusted net profit hit almost $6 billion in 2025, up 43.8% year on year.
Known for its smartphones and EVs, the brand is a household name in China. The company is now looking abroad by accelerating shipments to Western Europe and North America.
Xiaomi has been one of the Chinese brands that has been most visible in incorporating biomaterials into its devices to appeal to green consumers.
Its 14T smartphone, for example, features both bio-composites and recycled materials.
The back shell of the model is available in either Glass Panda-X II or a PU fiberglass board with bio-based PU. The biobased PU is Xiaomi’s own, made from lemon fibre and waste plastic bottles.
The phone’s solid buttons on the phone, like the volume and power key, as well as the antenna bracket, speaker box, and front cam bracket, are made partially from a biobased polycarbonate known as SABIC bio-based PC-1414B. It is made from waste wood and paper.
Xiaomi’s other partially biobased device is the Redmi Note 14 Pro, a phone that features a bio-composite leather covering on its back. The leather is designed for comfort, as well as to offer a surface that minimises visible fingerprint marks.
In the Redmi Note 14 Pro, Xiaomi uses a proprietary vegan leather. It is made up of three layers: the first is the one the consumer makes contact with, the second is the actual leather layer, made from 26% plant-based content. The base layer is made from oil-based PET.
BYD
BYD overtook Tesla as the world’s biggest EV seller in 2025, with sales ranging across 70 countries. The company’s capacity does not end at vehicles and their batteries – it also makes phone and automobile parts.
Across its manufacturing portfolio, BYD is investing in material innovation. This year, the company accelerated its R&D ambitions by signing a partnership with German chemicals producer Covestro. The strategic partnership is to co-develop advanced polymer materials across electric vehicles, batteries, and emerging technologies.
The partnership framework includes joint innovation initiatives, technology co-development programs, and strategic investment opportunities designed to accelerate material breakthroughs.
Their memorandum of understanding is wide-ranging. BYD and Covestro are set to deepen their collaboration across new energy vehicles, power batteries, public transportation, energy storage systems, and emerging technology applications.
This collaboration could offer a major break for biomaterials in the world’s top EV production line. Covestro is a major manufacturer of biobased chemicals and materials and the MoU underlined a shared commitment by both companies to advance low carbon and circular material solutions for BYD’s automobile lines.
The agreement also specifies that Covestro’s Circular Intelligence range, made with at least 25% “alternative raw materials”, will form a key part of the R&D geared toward sustainability.
SAIC Motor
SAIC Motors has opted for bamboo in its car parts, turning this highly sustainable, traditional biomass into a range of high-performance composites.
SAIC introduced bamboo fibre-reinforced composites into the interiors of more than 20 production vehicle models in 2026. This included 11 car part categories including headliners, seatback panels, trunk trim, sun visors, and central floor carpets.
Like many other firms covered in this list, SAIC makes their own biobased supply.
It operates one bamboo-fibre production line and two composite-panel lines in Guangxi, with annual capacity of around 200,000 square metres of panels and 4,000 tonnes of raw fibre.
Vertical integration is a strategic choice. Setting up their own high-tech bio-processing capacity is something these capital-rich firms can afford. Over the long run, it cuts costs compared to buying from an external supplier.
SAIC’s sustainability commitment also extends to packaging. Currently, SAIC Motor has achieved a 100% use of recyclable, reusable, or biodegradable eco-friendly materials for all packaging tools. The company says that this has resulted in an annual reduction of approximately 6,000 tons in packaging volume.
Huawei
Tech firm Huawei was one of the early starters when it came to biobased components. The firms began producing biobased device components all the way back in 2013.
Since then, it has used recycled and bio-based plastics widely in Huawei smartphones, smart watches, augmented reality or virtual reality devices, Bluetooth earphones, mobile routers, and other products.
Around a third of the bio-based plastics that the company uses comes from the feedstock castor oil. In packaging, the company uses 100% biodegradable soy ink.
For many Chinese tech companies, the use of biobased materials is driven by practical concerns. At Huawei, biobased adoption aims at mitigating the supply risks associated with oil plastics in a country that lacks its own reserves. Investment into sustainable materials can also drive cost cutting and optimisation across the business.
These two practical concerns – costs and supply security – apply especially to Huawei’s sustainable packaging practices.
In 2025, Huawei developed a new pulp molding technique for packaging. This custom aqueous oil and pulp molding solution aimed to replace plastics with their own paper material. An in-house packaging solution cuts costs over the long run while going bio cuts reliance on plastic imports.
So far, the new packaging has been applied to the nova 14 Ultra smartphone packaging. The company says it has plans to use the packaging on other devices.
Compliance, supply security, green demand
There are three major factors pushing Chinese consumer firms towards biobased solutions.
Compliance with foreign regulations, both existing and potential, is one factor.
Tech firms in China are increasingly selling abroad, particularly in the EU, due to lacklustre domestic consumption. With EU environmental regulations tightening around packaging and personal devices, Chinese firms will have to reach for innovative low-carbon materials to anticipate regulations.
Then there is China’s resource dependence. Relying on oil plastics is a supply risk for producers in a nation that lacks large oil reserves. Self-sufficiency and resource sovereignty has been the watchword of Chinese industry ever since the founding of the People’s Republic of China.
In the last 15 years, China’s drive for industrial self-sufficiency became visible in energy, building a world-leading domestic solar industry. Now, by pioneering in biobased specialty chemicals, the country looks better placed than ever to cut dependence on imported materials.
Similarly for Chinese producers today, biobased adoption and R&D are investments in the future. The ability to turn to biomaterials and circular feedstock wards against shocks to the fossil supply chain, such as sanctions or war.
Then there is domestic demand from consumers for greener products. Consumer reports indicate that Chinese consumers, particularly those at the upper end of the income scale, are increasingly willing to spend a premium on environmentally sensitive products.
Why does it matter?
China’s importance in the biobased markets is both by virtue of its sheer size – it’s where 17% of the world’s population lives – and its rapid industrial build-out.
The biobased rollout in individual Chinese tech firms may seem relatively limited: bio-composite are only found in specific parts, in specific devices.
However, the scale of production is not negligible. When a brand of Xiaomi or BYD’s heft incorporates biobased parts, it adds a high volume of demand that ripples right the way through the value chain.
Whether in biomass feedstock or chemicals, a customer this big encourages new capacity, lower prices, and robust new biobased supply chains.
A market to watch
The motives are diverse yet the trend is undeniable: Chinese consumer giants are set to become one of the biggest drivers of biobased demand worldwide.
There is practical urgency behind the search for alternative materials among China’s consumer brands.
This year, China’s vital petrochemical imports from the Middle East came under threat from the US-Iran war. Independence from global supply chains is increasingly becoming an objective of corporate planning. Biobased materials offer this supply security, allowing producers to draw on domestic biomass.
Incorporating lower carbon materials is also more likely to unlock highly regulated markets like Western Europe, where many Chinese consumer tech firms are targeting to offset weaker domestic growth.
Further expansion in tech biobased demand will depend on several factors, including Chinese access to the critical European market. This is the region where sustainability regulations are among the most stringent.
Geopolitics will play a role too. US tariffs over the last year and a half have only buttressed Chinese policies around resource independence.
In January 2026, the Chinese government published a list of priority projects earmarked for funding. It included capacity for biomaterials made using non-grain feedstocks.
With the government backing biomaterials like this as a means to maximise domestic resources, consumer tech adoption is only set to accelerate.
The post The Chinese tech giants driving biobased demand appeared first on World Bio Market Insights.